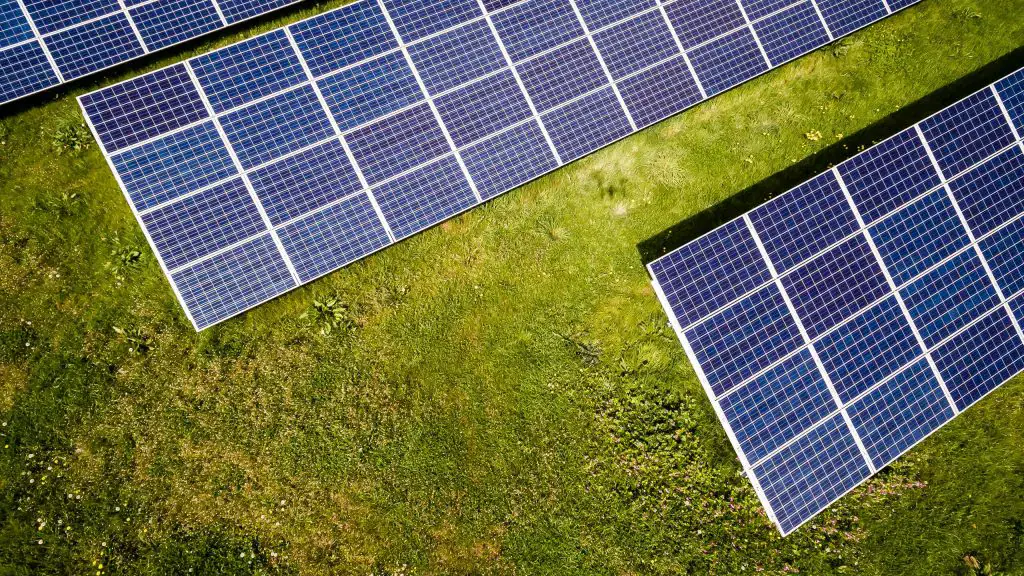
Africa's renewable energy transition is increasingly driven by households and businesses generating electricity for their own use. The International Energy Agency's (IEA) Renewables 2026 report identifies this shift as a major driver of the continent's clean power expansion. Distributed solar is expected to account for nearly two-thirds of new solar photovoltaic (PV) capacity in sub-Saharan Africa between 2026 and 2031. The IEA forecasts that global renewable electricity capacity will grow by almost 4,800 gigawatts (GW) over the period.
The IEA has revised upwards its renewable capacity forecast for sub-Saharan Africa by 54 per cent, or 33 GW, compared with last year's outlook. Almost all this upward revision comes from distributed solar, whose forecast has increased by 42 GW. Utility-scale solar has been revised downwards by nearly 7 GW, reflecting financing difficulties, offtaker risks and inadequate transmission infrastructure. This adjustment signals a significant change in how renewable energy is developing across the region.
Rather than depending exclusively on large grid-connected projects, more consumers are turning to rooftop, commercial and off-grid solar systems to address unreliable electricity supply, high tariffs and rising diesel costs. Nigeria, South Africa and Kenya are among the leading markets for this consumer-driven expansion. The scale of the opportunity is particularly evident in off-grid solar, with sub-Saharan Africa expected to install more than 21 GW of additional off-grid solar capacity between 2026 and 2031.
South Africa continues to dominate the region's utility-scale solar outlook, accounting for 48 per cent of projected additions. Its procurement programmes, corporate power purchase agreements and arrangements allowing private generators to use the national grid support investment. Elsewhere, Kenya, Namibia and Senegal are advancing through dedicated procurement rounds and other support mechanisms.
The expansion of distributed solar does not remove the need for large-scale generation. Industrial development, urbanisation and growing populations require electricity systems capable of delivering power consistently and at scale. The IEA identifies weak grid infrastructure, transmission bottlenecks, uncertain procurement arrangements and financially constrained utilities as continuing obstacles to utility-scale projects.
There are challenges in measuring solar growth, with Ember estimating that Africa installed 12 GW of solar capacity in 2025, compared with the IEA's estimate of 6.2 GW. Financing remains central to the transition, with Africa attracting only about 3 per cent of global energy investment despite accounting for roughly one-fifth of the world's population. The higher cost of capital for African energy projects can be two to three times that in advanced economies.
Regional electricity trade offers another opportunity to strengthen supply, with the World Bank's US$12 million RETRADE SAPP programme supporting technical assistance and institutional capacity across the Southern African Power Pool. Distributed solar can help address the electricity-access challenge, but access must be accompanied by affordability, reliable equipment and services that can support productive activities. The real test will be whether governments, utilities and investors can build the infrastructure, financing arrangements and regulatory frameworks needed to turn additional capacity into dependable power.
Key points
- Distributed solar is expected to account for nearly two-thirds of new solar photovoltaic (PV) capacity in sub-Saharan Africa between 2026 and 2031.
- The IEA forecasts that global renewable electricity capacity will grow by almost 4,800 gigawatts (GW) over the period.
- Sub-Saharan Africa accounts for more than 560 million people without electricity, representing the overwhelming majority of the global access deficit.
Reporting sources
- IEA Renewables 2026: Distributed Solar Drives Africa’s Clean Power Growth · African Leadership Magazine