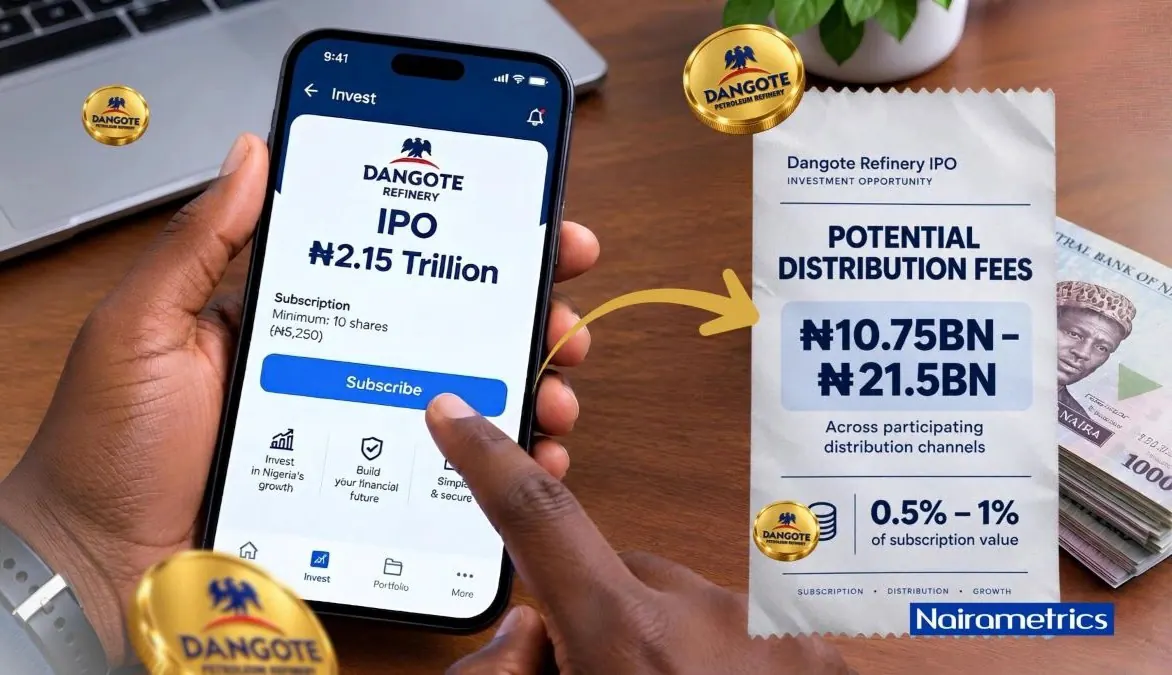
The Dangote Refinery Initial Public Offering (IPO) opened on September 14, sparking excitement among Nigerian investors. The opportunity to own a stake in one of Africa’s largest industrial assets is significant. However, experts are cautioning small investors with a short-term investment horizon to approach with care. This caution is not a warning against participating in the IPO, but a reminder that a great company does not automatically make every entry price attractive.
At ₦525 per share, investors are being asked to value Dangote Refinery at a very substantial level. For a long-term investor, the refinery’s scale, strategic importance, expansion plans, and potential to become a major energy hub for Africa may justify such optimism. The company reportedly recorded about $1.82b in profit after tax in the first half of 2026, following a loss in the previous year. This turnaround is impressive, but investors should be careful about assuming that such exceptional earnings will automatically continue at the same level.
Refining profitability is influenced by global oil prices, crude supply, product prices, and refining margins. The current geopolitical tensions involving Iran and the wider Middle East have disrupted energy markets and contributed to tight supplies and elevated refining margins. As these disruptions eventually ease, global refining conditions could normalise. The refinery may remain highly profitable, but its earnings could be lower than the extraordinary levels currently being reported.
Another consideration is competition. Dangote Refinery currently enjoys an enormous competitive advantage because of its scale and limited refining capacity in Nigeria. However, that advantage should not be mistaken for a permanent monopoly. High profits and a large market opportunity are likely to attract competitors. Existing refineries can increase production, while new refining and petrochemical projects may emerge across Nigeria and Africa.
As competition increases, market share and refining margins could come under pressure. For the small short-term investor, the greatest risk may therefore be buying into the initial excitement and then experiencing a price correction. This is a familiar pattern in highly anticipated offerings and investments. The initial enthusiasm can push prices beyond levels justified by near-term fundamentals, after which early investors take profits and the market reassesses the valuation.
Similar patterns have been observed in other high-profile investments, including the market reaction surrounding SpaceX-related investment opportunities, where intense enthusiasm has at times been followed by valuation adjustments. Dangote Refinery may ultimately become an outstanding long-term investment. Its size, strategic importance, and expansion potential are difficult to ignore. But tomorrow’s IPO should not be viewed as a situation where investors must rush in simply because they fear missing out.
For the small, short-term investor, patience can be an investment strategy. The objective should not simply be to own Dangote Refinery, but to own it at a price that provides sufficient room for profit. Investors should consider sustainable earnings, future competition, normalised refining margins, and the possibility of post-listing profit-taking. The September 14 IPO is therefore best approached with cautious optimism rather than fear or excessive excitement.
Key points
- Experts warn short-term investors to exercise caution when investing in the Dangote Refinery IPO.
- The refinery's profitability may be influenced by global oil prices, crude supply, product prices, and refining margins.
- The IPO is best approached with cautious optimism rather than fear or excessive excitement.