Dangote Cement, Nigeria's largest cement producer, has reported a 31.2% year-on-year increase in profit after tax to ₦974.8bn (US$714M) for the nine months to 30 September 2026. This growth is attributed to a 19.6% rise in revenue to ₦3.77tn (US$2.77bn) and a 41.5% increase in profit before tax to ₦1.47tn (US$1.08bn). The company's unaudited results, filed with the Nigerian Exchange, also show a 33.2% rise in earnings per share to ₦58.37.
The company's EBITDA advanced 23.7% to ₦1.77tn (US$1.29bn), with the EBITDA margin widening to 46.8%, up from 45.3% in the first nine months of 2025. This improvement in margins reflects tighter cost control and stronger domestic pricing. Additionally, the company completed its deleveraging programme by September 2026, moving into a net-cash position during the period. This significant reduction in debt has strengthened the company's balance sheet.
Dangote Cement's net finance costs fell sharply to ₦97bn from ₦208.9bn a year earlier, driven by its improved financial position. The company generated ₦1.26tn (US$923M) in free cash flow over the nine months, while dividends paid during the same period totalled ₦753.8bn. This gap between free cash flow and dividends signals meaningful capacity for further shareholder returns or capital deployment.
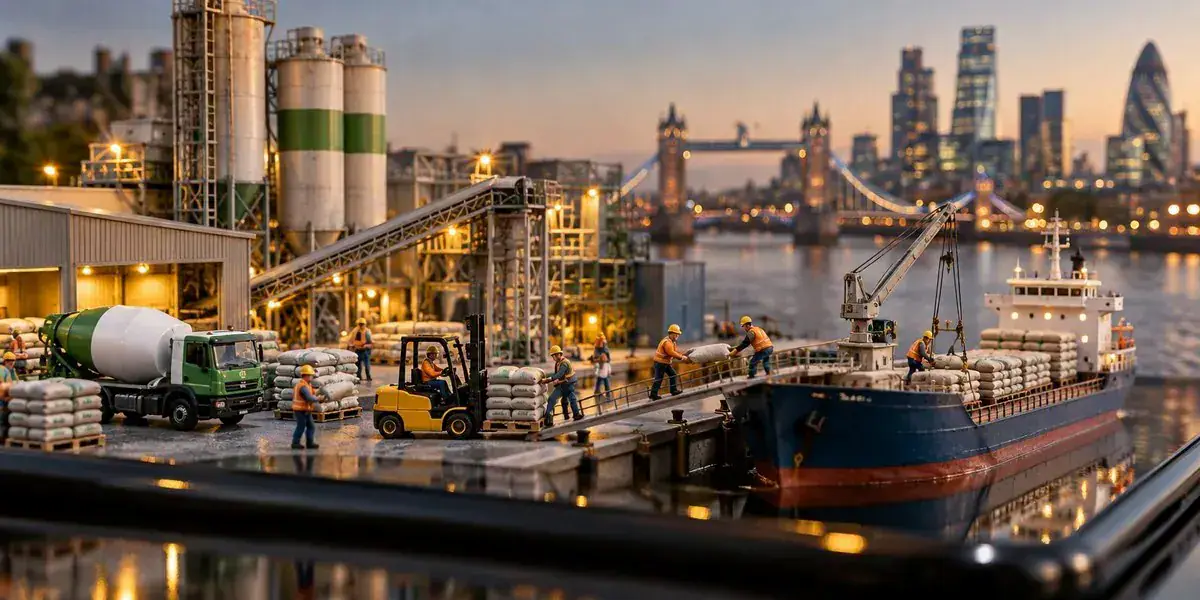
The proposed secondary listing of Dangote Cement in London is expected to open the company up to a broader pool of international capital. Existing shareholders are considering a London debut as early as November 2026, subject to market conditions. This move follows the separate Dangote Petroleum Refinery IPO, which drew investors from 119 countries and secured between US$1.5bn and US$1.6bn in commitments.
Group cement sales rose 9.4% year on year to 22.1 million tonnes in the nine months to September 2026. Nigeria remained the dominant earnings driver, with exports of cement and clinker from Nigeria also increasing. However, Ghana and Cameroon recorded lower sales during the period, highlighting Nigeria's central role in the company's near-term earnings.
The IMF's upwardly revised growth forecast for Nigeria adds a supportive macro backdrop for Dangote Cement's growth plans. Rising domestic demand for construction materials aligns with the company's capacity expansion plans across the continent. Pan-African volumes contributed to overall growth, supporting the longer-term growth thesis.
As Dangote Cement prepares for its London listing, investors are watching closely. A cash-backed balance sheet materially improves the investment case for any international listing. With lower debt now a key focus, the company's strategy seems to be paying off, positioning it for further growth and potential shareholder returns.
Key points
- Dangote Cement reports 31.2% rise in 9-month profit after tax to ₦974.8bn.
- The company moves into a net-cash position ahead of a proposed secondary listing in London.
- Group cement sales rise 9.4% year on year to 22.1 million tonnes in the nine months to September 2026.