Britain's property market has experienced a tumultuous year, with the Gulf conflict driving oil prices past $100, rising inflation forecasts, and vanishing rate cuts. According to UK market research and the RICS commercial property monitor, capital values turned negative, and first-quarter deal volumes hit their lowest in nearly three years. This downturn has led to quiet loans turning into defaults and enforcement actions. The UK's Financial Times reports that the family of Mahdi Al Tajir, once ranked the richest man in Scotland, faces defaults and creditor action across its property empire.
The family's property empire, including Highland Spring, is facing significant challenges. Creditors have repossessed a London home and are pursuing claims against family members. A Mayfair bridging specialist, Cohort Capital, holds defaulted mezzanine debt of R7.7bn (£347.5m) against the Park Tower hotel and up to R3.8bn (£171m) against Arlington House. Cohort Capital also lent against family properties, including a Kent castle and a West Sussex pub. The company's co-founder previously described a deal with the firm as proof of its "mettle in completing complex lending deals for the country's most iconic residential properties".
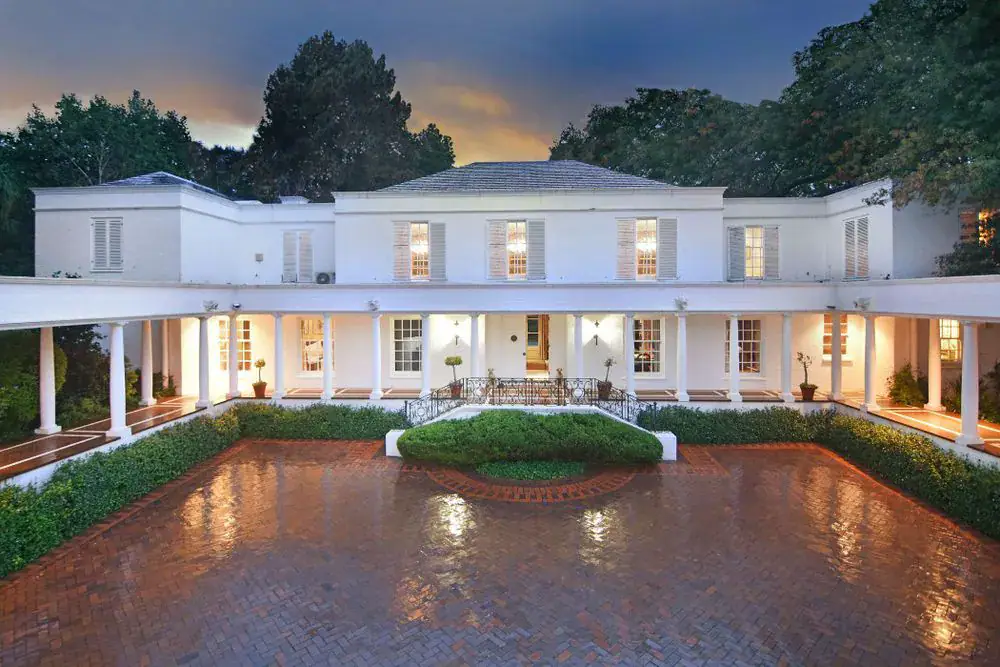
The sequence of events surrounding the family's properties is concerning. The money against the family's two flagship London properties was lent in late 2025. However, the Arlington House debt was in default within months, and the Park Tower facility within a year. Creditors are now enforcing, and the trophy assets are heading for the market. The family's assets, including 18 Carlton House Terrace, are being sold for R2.8bn (£125m). This situation highlights the risks associated with bridging loans, which usually carry double-digit annual rates and are meant as a stopgap until a sale or refinancing.
Bridging loans can be problematic in a falling market. Both exits, sale or refinancing, narrow exactly when the meter runs fastest, as rates step up on default and exit fees grow with the debt. Additionally, both exits usually need the lender's consent. A borrower who wants to repay can only do it by selling or refinancing, and if the lender controls the road out, they decide whether the borrower leaves. This dynamic raises questions about the strategy of "loan to own," where lenders may have an eye on ending up with the asset.
Critics of the bridging sector argue that these loans are, by definition, loans to borrowers mainstream banks will not finance, at double-digit rates a stretched borrower will struggle to carry. This means the lender is pricing the possibility of failure from day one, and in a falling market, failure hands them a trophy asset at a discount. The lack of conduct regulation among unregulated lenders, known as "Annex 1" lenders, raises concerns about how borrowers are treated.
The UK has already seen the consequences of failure in this market. In March, the bridging lender Market Financial Solutions collapsed, leaving its creditors facing an alleged shortfall of R29bn (£1.3bn). This collapse prompted the regulator to demand answers from around 900 unregulated firms. However, the crackdown triggered is focused on financial crime, not on how borrowers are treated. The line between a lender and a buyer in waiting is not patrolled by any regulatory body.
For investors, including those from South Africa, it is essential to exercise caution. Six questions were raised in August, and a seventh has been added: before signing, know exactly how to get out, on what timetable, and whose consent the exit needs. Markets recover, but rules catch up more slowly. Until then, the contract signed is the only shield investors hold.
Key points
- Unregulated lenders in the UK property market pose significant risks to borrowers.
- The UK's property market has experienced a downturn, with capital values turning negative and deal volumes hitting a low.
- Bridging loans can lead to a "loan to own" strategy, where lenders may end up with the asset.