Kenyan entrepreneurs seeking financing from banks are finding that a promising business idea is no longer enough to secure a loan. Instead, lenders are placing greater emphasis on a company's ability to generate sufficient cash to repay the borrowed amount. This shift in approach is being driven by the need for banks to assess the creditworthiness of small and medium-sized enterprises (SMEs) more accurately.
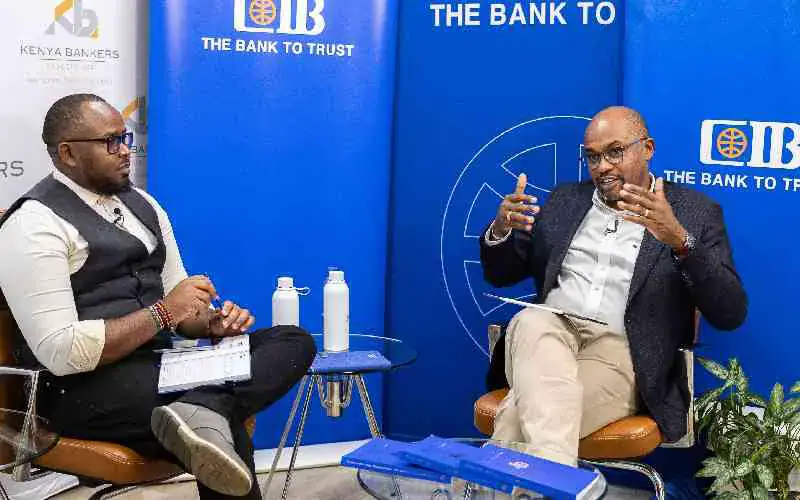
According to Tirus Mwithiga, Chief Executive Officer of CIB Kenya, banks are primarily interested in a business's capacity to service its debt rather than the enthusiasm or ambition behind an entrepreneur's idea. Mwithiga notes that entrepreneurs seeking credit must demonstrate how their businesses make money, manage operating expenses, and generate sufficient cash to meet their financial obligations.
To achieve this, SMEs need to maintain accurate financial records, separate personal finances from business accounts, and understand their cash flow. A business owner who cannot clearly account for revenue, expenditure, and profitability makes it difficult for a lender to establish whether the enterprise can sustain additional debt.
Mwithiga emphasizes that having a viable business idea is only the starting point. Entrepreneurs must also understand their target markets, identify the costs of operating in those markets, and demonstrate how their ventures will generate consistent income. He urges business owners to formalize their operations, establish effective management systems, and recruit people with the necessary skills to manage different aspects of their enterprises.
The Kenya Bankers Association's (KBA) State of the Banking Industry Report 2026 shows that 73.4% of outstanding micro, small, and medium-sized enterprise (MSME) credit was uncollateralized as of December 2025. This represents 1.26 million loans held by 707,211 borrowers, highlighting the extent to which banks are extending credit without conventional collateral.
However, inadequate collateral, poor credit scores, and difficulties meeting repayment obligations continue to constrain access to financing for many small businesses. Mwithiga cautions entrepreneurs against borrowing beyond their actual business requirements, warning that excessive debt can place unnecessary pressure on operations and undermine the ability to repay.
Mwithiga advises businesses to borrow only what they need and pay it back quickly to establish a credit history and build confidence with lenders. He also encourages entrepreneurs to build relationships with their banks before making loan applications, as engaging with relationship managers can help business owners understand lending requirements and identify gaps in their financial management.
Key points
- Banks in Kenya are prioritizing cash flow over collateral when lending to small businesses.
- Kenyan entrepreneurs must demonstrate their business's ability to generate sufficient cash to repay loans.
- The Kenya Bankers Association reports that 73.4% of outstanding MSME credit was uncollateralized as of December 2025.