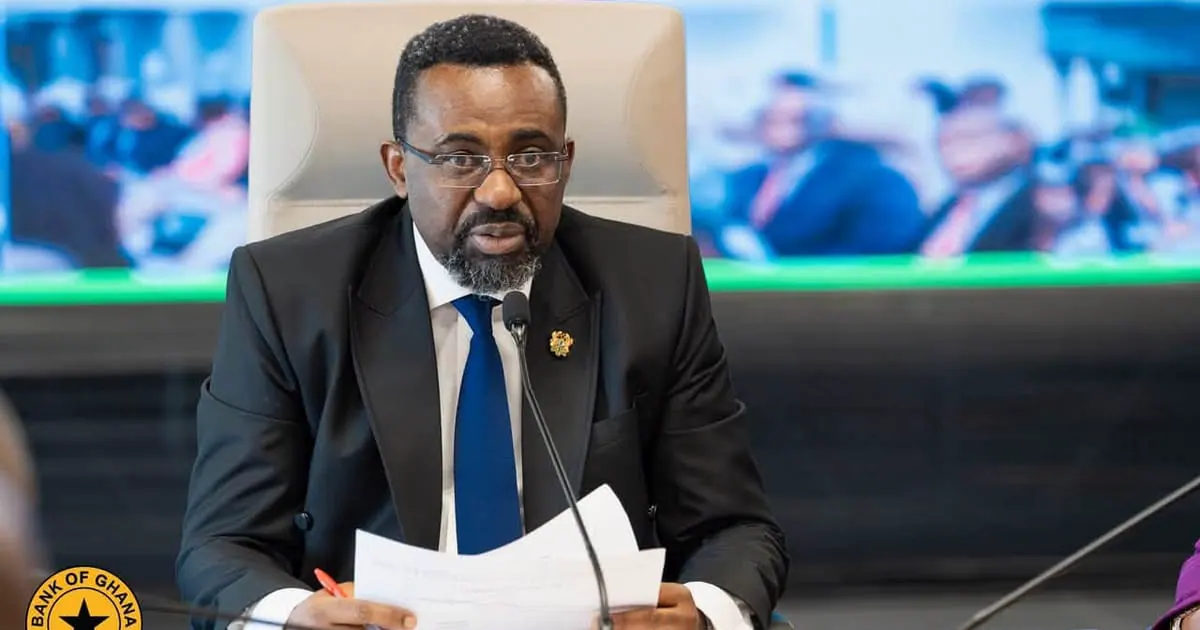
The banking sector in Ghana remains solvent, profitable, and liquid, with improving asset quality, according to Dr. Johnson Pandit Asiama, Governor of the Bank of Ghana. As of August 2026, the total assets of the sector increased by 20.5 percent, year-on-year, to GH¢500.2 billion. This growth was supported by robust deposit mobilisation and an increase in other funding sources. The sector's performance indicates a positive trend in the country's financial system.
Dr. Asiama highlighted that the Capital Adequacy Ratio of the banking system improved to 19.1 percent in August 2026 from 18.3 percent in August 2025. This improvement in asset quality was further reflected in the Non-Performing Loan (NPL) ratio, which declined to 15.7 percent from 20.8 percent over the same period. The strong rebound in credit growth contributed to this decline. These indicators suggest that banks in Ghana are strengthening their financial positions.
Despite the improvement in asset quality, Dr. Asiama noted that credit risk remains elevated. To address this, banks are expected to adhere to the NPL guidelines to bolster confidence in the financial system. This move aims to ensure that banks maintain high standards in their lending practices and manage their credit portfolios effectively. By doing so, the stability and confidence in the banking sector can be further enhanced.
On the monetary front, reserve money grew strongly by 29.7 percent, year-on-year, in August 2026, compared with 4.5 percent in August 2025. This expansion was primarily driven by growth in net domestic assets, reflecting the impact of policy changes on reserve requirements. However, net foreign assets declined, which helped moderate the overall growth in reserve money. These developments indicate a shift in the monetary policy landscape.
The broad money supply also saw a significant increase, growing by 20.4 percent, year-on-year, in August 2026, up from 16.6 percent in August 2025. Additionally, interest rates on Government’s short-term instruments moderated further in August 2026. The 91-day Treasury bill rate declined to 5.4 percent from 10.3 percent a year earlier. These changes suggest a more accommodative monetary policy stance.
The average lending rate for the banking sector declined to 15.9 percent from 24.2 percent over the same comparative period. This decrease, coupled with the low-interest rate environment and ease in credit stance by banks, contributed to higher credit growth in the banking sector. Private sector credit growth rebounded to 35.5 percent in August 2026 from 13.3 percent in August 2025, indicating a significant pick-up in lending activities.
In real terms, private sector growth was 29.0 percent, relative to 1.7 percent over the same comparative period. This substantial increase in credit growth reflects a positive trend in the financial sector and the broader economy. The rebound in private sector credit growth is a welcome development, suggesting that businesses and individuals are accessing more credit to finance their activities.
Key points
- Banks in Ghana are expected to adhere to NPL guidelines to manage elevated credit risk.
- The banking sector's asset quality improved, with the NPL ratio declining to 15.7 percent.
- Private sector credit growth rebounded to 35.5 percent in August 2026.