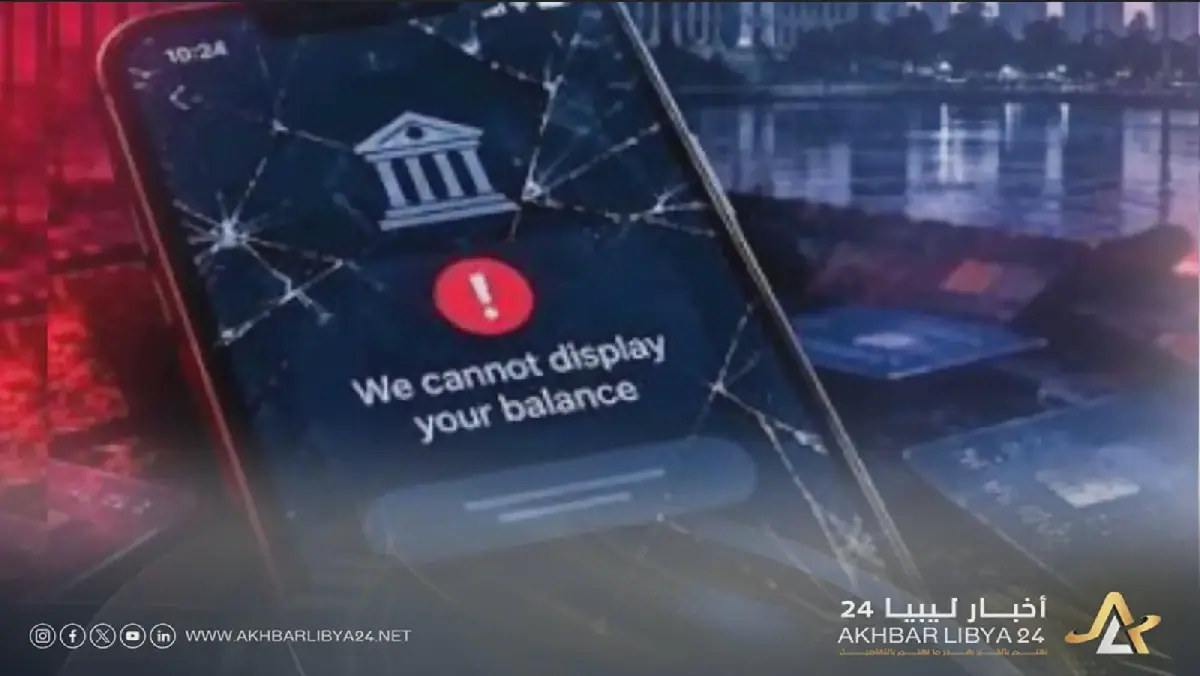
Recent developments in Paraguay and Japan have raised concerns about the risks of relying on digital banking and centralized financial systems. In Paraguay, a digital bank called "Banco Oigno" faced financial difficulties, leading to a freeze on customer accounts and a crisis that affected millions of people. The bank's collapse highlighted the risks of relying on a single financial institution for everyday transactions.
In Japan, a technical glitch affected 128 credit unions, causing disruptions to banking services, including withdrawals, deposits, and transfers. The incident showed how a single technical issue can impact multiple financial institutions that rely on the same infrastructure. The affected institutions were part of a larger network of 236 credit unions, highlighting the interconnectedness of modern banking systems.
The incidents in Paraguay and Japan have sparked questions about the safety and security of digital banking. While digital banking offers many benefits, including increased efficiency and accessibility, it also creates new risks. One of the main concerns is that digital banking systems can be vulnerable to technical failures, cyber attacks, and other disruptions that can leave customers unable to access their funds.
The issue of digital banking safety is closely tied to the concept of fractional reserve banking, where banks use depositors' funds to make loans and investments. This system can create new money and stimulate economic growth, but it also carries risks. If too many depositors try to withdraw their funds at the same time, banks may not have enough liquidity to meet demand, leading to a crisis.
Another concern is the potential for monopolization in the banking sector. When a small number of institutions control the majority of the market, it can lead to a lack of competition and innovation. This can result in higher fees, lower interest rates, and reduced services for customers. In addition, a monopoly can make it difficult for customers to switch to alternative providers if they are dissatisfied with their current bank.
The Paraguayan and Japanese incidents highlight the need for a balanced approach to banking regulation. While regulation is necessary to protect customers and maintain financial stability, over-regulation can stifle innovation and competition. A balanced approach would ensure that banks are able to operate safely and efficiently, while also providing customers with access to a range of services and providers.
Ultimately, the goal of banking regulation should be to protect customers and promote financial stability, while also allowing for innovation and competition. This can be achieved by implementing robust regulatory frameworks, improving transparency and accountability, and promoting financial literacy and education. By taking a proactive and balanced approach to banking regulation, governments can help to mitigate the risks associated with digital banking and promote a stable and sustainable financial system.
Key points
- A balanced approach to banking regulation is necessary to protect customers and promote financial stability, while also allowing for innovation and competition.