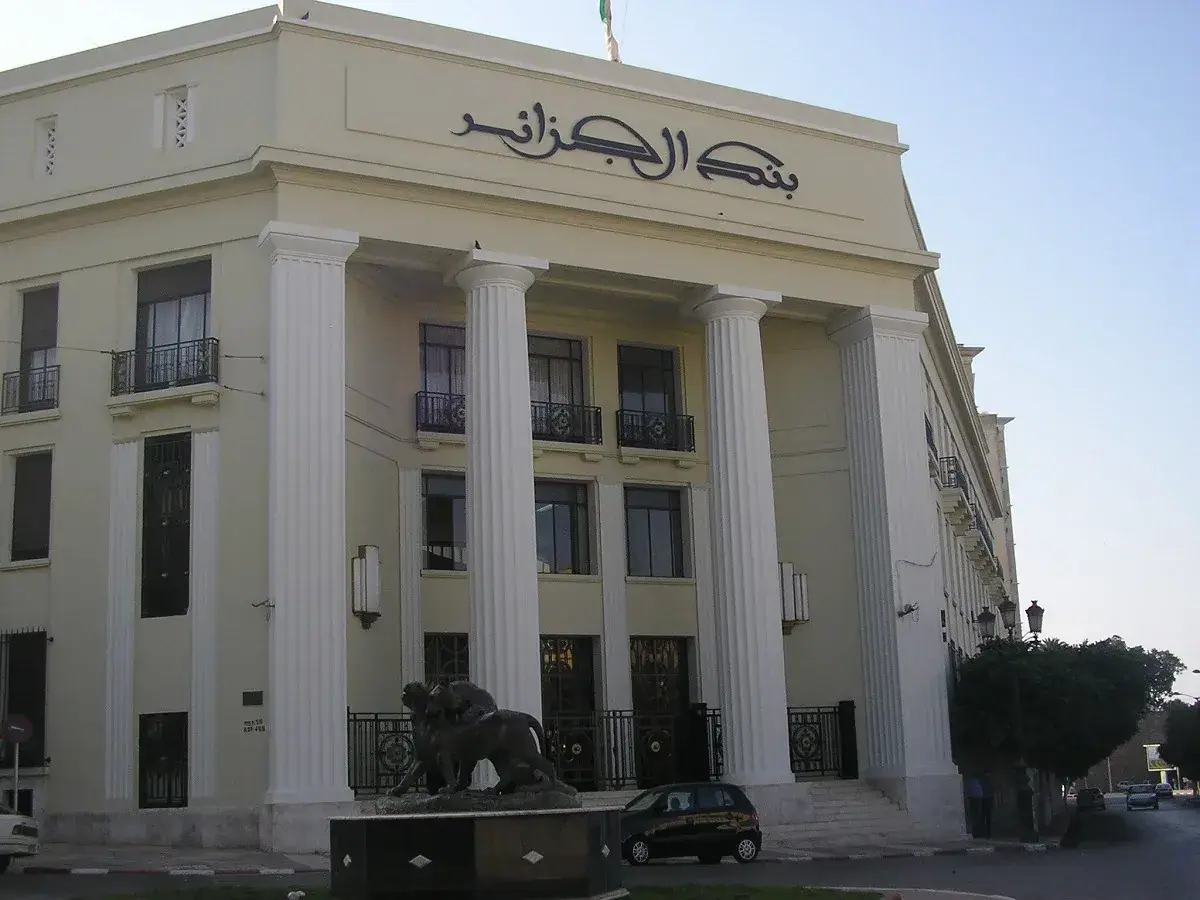
The Banque d'Algérie has published a new regulation governing gold transactions in the local market. The regulation, published in the Official Journal No. 77, allows banks and financial institutions to buy and sell gold, open gold accounts, and provide gold-secured financing. The regulation aims to define the rules for gold transactions and the conditions for the Banque d'Algérie, banks, and financial institutions to intervene in the gold market.
The regulation, numbered 26-04 and dated September 17, 2026, implements the provisions of Articles 41 and 79 of Law No. 23-09 of June 21, 2023. It sets a 10% limit on the net gold position of banks and financial institutions relative to their regulatory capital. The regulation also defines the terms "gold," "eligible gold," "gold account," and "gold-secured financing." Eligible gold refers to gold that meets specific quality, purity, origin, and traceability requirements.
The regulation outlines the types of gold transactions that can be conducted by the Banque d'Algérie, banks, and financial institutions. These include buying and selling gold, opening gold accounts, and providing gold-secured financing. The Banque d'Algérie can also acquire gold from authorized agencies and institutions. The characteristics of eligible gold for these transactions will be specified by instruction from the Banque d'Algérie.
Banks and financial institutions can conduct gold transactions with individuals and legal entities within the limits of their activities and regulatory conditions. These transactions include buying and selling gold, depositing and conserving gold, opening gold accounts, and providing gold-secured financing. The Banque d'Algérie will specify the characteristics of eligible gold and the conditions for opening and operating gold accounts.
The regulation requires banks and financial institutions to maintain a net gold position that does not exceed 10% of their regulatory capital. Gold-secured financing provided by banks and financial institutions is subject to regulatory requirements for capital adequacy, risk diversification, and loan classification. The regulation also specifies that gold received as collateral has a risk weight of 80%.
The regulation addresses the treatment of gold-related assets and liabilities in calculating liquidity coefficients. It also states that gold accounts are not covered by the bank deposit guarantee system, and banks and financial institutions must subscribe to an insurance contract covering gold account risks. The evaluation and valuation of gold from the local market must follow national official standards.
The regulation emphasizes the importance of internal controls for gold transactions to prevent money laundering, terrorism financing, and proliferation financing. Banks and financial institutions must implement procedures to verify the quality and purity of gold, establish its origin, and ensure its traceability. They must also control the conformity and reliability of related documentation.
Key points
- The Banque d'Algérie has set a 10% limit on the net gold position of banks and financial institutions relative to their regulatory capital.
- The regulation requires banks and financial institutions to implement internal controls to prevent money laundering and other financial crimes.
- The regulation defines the terms and conditions for gold transactions in the local market, including eligible gold, gold accounts, and gold-secured financing.