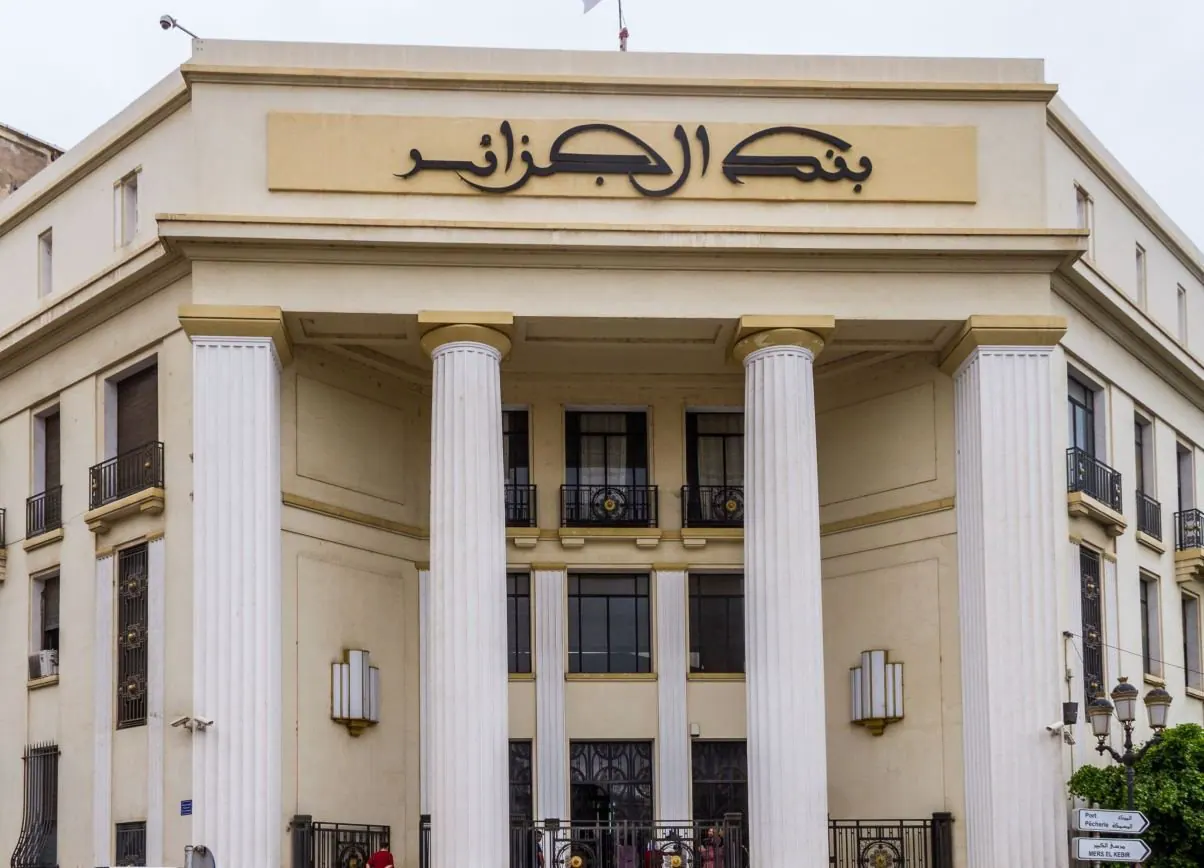
The Banque d'Algérie, Algeria's central bank, has established conditions for the exercise of factoring activities by banks and financial institutions through Regulation No. 26-03, published in the Official Journal No. 67 on August 13, 2026. The regulation, signed by Governor Mohammed Lamine Lebbou, defines the terms and conditions for factoring operations. Factoring, or affacturage, involves the transfer of commercial receivables from a client to a bank or financial institution, known as the factor, which pays the client a fixed amount and assumes the risk of non-payment.
According to the regulation, factoring operations are considered credit transactions and are therefore reserved for licensed banks and financial institutions. The regulation specifies that only commercial receivables evidenced by invoices or equivalent documents, established in accordance with applicable laws and regulations, are eligible for factoring. To be eligible, receivables must meet certain conditions, including being certain, liquid, and determined in amount, and not being contested by the debtor.
The regulation outlines several key criteria for the eligibility of commercial receivables, including that they must have a payment term of less than six months from the date of invoicing, not be extinguished by payment or compensation, and be freely transferable without any legal or contractual restrictions. Receivables must also not be encumbered by any liens or charges that could affect the factor's rights and must not relate to a debtor in a state of cessation of payments or judicial restructuring.
The regulation requires that factoring operations be based on a written contract concluded before any financing is provided by the factor. It also stipulates that any contract that aims to finance receivables that have already been financed under another factoring contract is null and void. The subrogation of the factor in the client's rights and guarantees attached to the transferred receivables occurs automatically upon the provision of funds to the client.
The regulation specifies that the factor's remuneration for factoring operations includes a financing commission and a factoring commission, which covers the management, monitoring, and collection of transferred receivables, as well as, where applicable, coverage of the risk of non-payment. The factor is required to disclose its banking conditions for factoring operations to its clients and the public through appropriate means.
The regulation also provides that factoring operations must be accounted for in accordance with applicable regulatory provisions for banks and financial institutions. These operations are subject to the same classification and provisioning rules as other receivables. The commercialization of factoring products by banks and financial institutions must comply with existing regulatory procedures.
Finally, banks and financial institutions are required to declare data related to factoring operations to the central risk enterprise and household database, in accordance with applicable regulatory provisions. The regulation aims to establish a clear framework for factoring operations in Algeria, promoting transparency and stability in the financial sector.
Key points
- The Banque d'Algérie has set conditions for factoring operations to promote transparency and stability in the financial sector.
- Only commercial receivables that meet specific criteria are eligible for factoring.
- The regulation requires factoring operations to be based on a written contract and be accounted for according to applicable regulatory provisions.